

Calculate your loan EMI
10 lakh · allowed range ₹1,000 to ₹10 crore
Fixed annual rate, 0% to 36%
60 months · allowed range 1 to 360 months
- Monthly EMI
- ₹21,247.04
- Principal amount
- ₹10,00,000.00
- Total interest
- ₹2,74,822.68
- Total amount
- ₹12,74,822.68
| Loan year | Principal paid | Interest paid | Total paid | Closing balance |
|---|---|---|---|---|
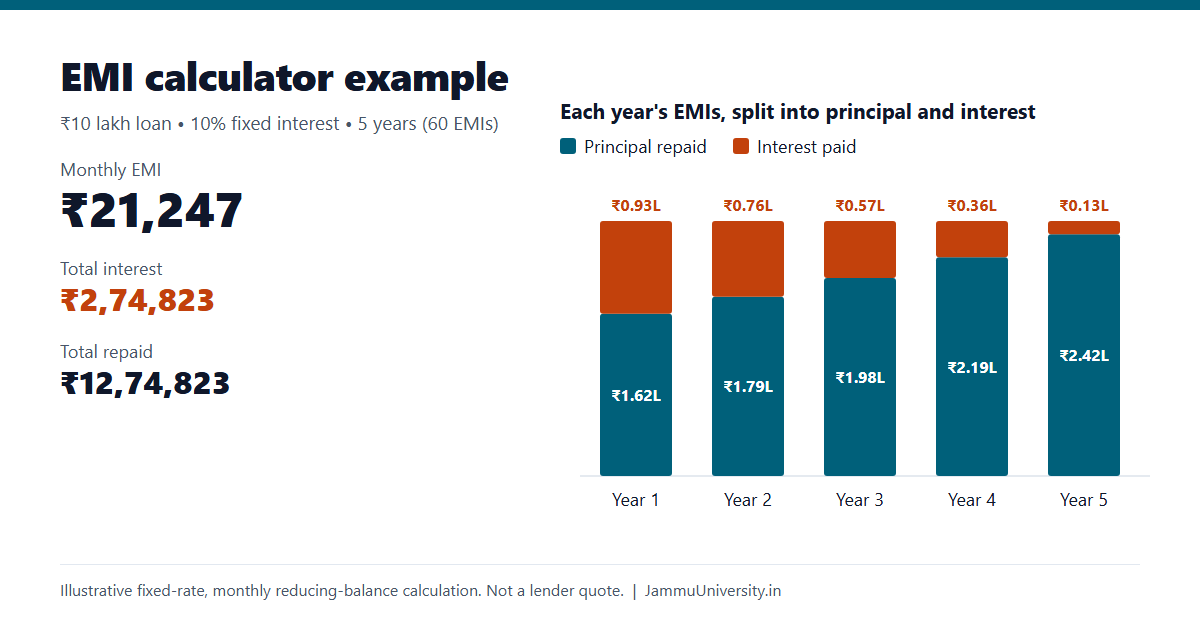
| 1 | ₹1,62,268 | ₹92,696 | ₹2,54,965 | ₹8,37,732 |
| 2 | ₹1,79,260 | ₹75,705 | ₹2,54,965 | ₹6,58,472 |
| 3 | ₹1,98,031 | ₹56,934 | ₹2,54,965 | ₹4,60,442 |
| 4 | ₹2,18,767 | ₹36,198 | ₹2,54,965 | ₹2,41,675 |
| 5 | ₹2,41,675 | ₹13,290 | ₹2,54,965 | ₹0 |
Estimate only, not financial advice. Example buttons use illustrative values, not lender rates. Fees, GST on fees, insurance, prepayments, rate changes and moratorium interest are not included.
This free EMI calculator estimates the monthly instalment on a home, personal, car or education loan. Enter the amount, interest rate and tenure to see your EMI, total interest and repayment schedule instantly.
It runs in your browser, so nothing you type ever reaches us. JammuUniversity.in is an independent news publication, not linked to the University of Jammu, any lender or the RBI.
How to use this EMI calculator
- First, type the loan amount or move the slider. Any amount from ₹1,000 to ₹10 crore works.
- Next, enter the annual interest rate quoted by your lender, between 0% and 36%.
- Then choose years or months and set the tenure. The limit is 360 months (30 years).
- Read the monthly EMI, total interest and total amount payable. They update as you type.
- Switch the schedule between yearly and monthly views. You can also use Download CSV to open the full monthly schedule in a spreadsheet.
The Home, Personal, Car and Education buttons only fill in example numbers so you can explore quickly. No lender offers these exact rates, so always replace them with the figures from your own loan offer.
What is an EMI?
EMI stands for equated monthly instalment. It is the fixed amount a borrower pays every month until a loan is fully repaid.
Each instalment has two parts. One part is interest on the amount still outstanding. The other part reduces the principal, which is the money you originally borrowed.
Because lenders charge interest on the outstanding balance, the interest share is largest at the start. Then, as the balance falls, more of the same EMI goes towards the principal. Lenders call this a reducing-balance loan, and it is the method this EMI calculator uses.
EMI calculation formula
For a fixed-rate loan repaid monthly, the standard formula is:
EMI = P × r × (1 + r)n ÷ [(1 + r)n − 1]
- P is the principal, or loan amount.
- r is the monthly interest rate. Divide the annual rate by 12, then by 100. For example, 10% a year gives r = 10 ÷ 1200 = 0.008333.
- n is the number of monthly instalments. For example, 5 years is 60 months.
If the interest rate is 0%, however, the formula does not work as written. In that case, the EMI is simply the principal divided by the number of months, and the EMI calculator handles this automatically.
Worked example: EMI on a ₹10 lakh loan
Suppose you borrow ₹10,00,000 at a fixed 10% annual interest rate for 5 years.
- Monthly rate: r = 10 ÷ 1200 = 0.0083333.
- Number of instalments: n = 5 × 12 = 60.
- (1 + r)60 = 1.645309 (rounded).
- EMI = 10,00,000 × 0.0083333 × 1.645309 ÷ 0.645309 ≈ ₹21,247.04.
| Item | Amount |
|---|---|
| Monthly EMI | ₹21,247.04 |
| Total interest over 5 years | ₹2,74,822.68 |
| Total amount repaid | ₹12,74,822.68 |
| Interest in the first EMI | ₹8,333.33 |
| Principal in the first EMI | ₹12,913.71 |
Notice that the first instalment is almost 40% interest. By the final month, in contrast, interest is only about ₹176 of the EMI. You can check these numbers yourself in the monthly schedule of the EMI calculator above.
How much is the EMI for a ₹10 lakh loan?
In short, it depends on the rate and the tenure. At a fixed 10% per year, the EMI on ₹10 lakh works out as follows.
| Tenure | Monthly EMI | Total interest |
|---|---|---|
| 3 years | ₹32,267 | ₹1,61,619 |
| 5 years | ₹21,247 | ₹2,74,823 |
| 7 years | ₹16,601 | ₹3,94,499 |
| 10 years | ₹13,215 | ₹5,85,809 |
| 20 years | ₹9,650 | ₹13,16,052 |
How interest rate and tenure change your EMI
Two inputs drive most of the cost of a loan. As a result, understanding them helps you compare offers sensibly.
Interest rate
A higher rate raises both the EMI and the total interest. For example, on ₹10 lakh over 5 years, the EMI is about ₹20,276 at 8%, ₹21,247 at 10% and ₹22,244 at 12%. Over the full term, that 4-point gap adds roughly ₹1.18 lakh of interest. So even a small rate cut is worth negotiating.
Loan tenure
Does a longer tenure reduce the EMI? Yes, but it usually costs more overall. Stretching ₹10 lakh at 10% from 5 years to 10 years lowers the EMI from about ₹21,247 to ₹13,215. However, total interest more than doubles, from about ₹2.75 lakh to ₹5.86 lakh. On the other hand, a shorter tenure means a higher EMI but a cheaper loan. Therefore, choose the shortest tenure whose EMI you can pay comfortably.
Principal vs interest: reading the amortization schedule
An amortization schedule lists every instalment with its interest part, its principal part and the balance left afterwards. The yearly view adds up twelve months at a time, while the monthly view shows each EMI separately.
In the ₹10 lakh example, the first year’s EMIs include about ₹92,696 of interest. In the fifth year, interest falls to about ₹13,290. This pattern explains why part-prepayments early in a loan save the most interest. It also shows why the outstanding balance falls slowly at first.
The calculator keeps full precision while working and only rounds the figures it displays. Finally, it adjusts the last instalment slightly so the closing balance ends at exactly zero.
Using the EMI calculator for different loans
Home loan EMI calculator
Home loans are large and often run for 15 to 30 years. Many use a floating rate, so the EMI or the tenure can change when the rate resets. For this reason, use it as a home loan EMI calculator: test several rates and see how a reset would change your instalment.
Personal loan EMI calculator
Personal loans are usually unsecured and shorter, and lenders often price them higher than secured loans. Because the tenure is short, the EMI can be high even for a modest amount. Check the total interest as well as the monthly figure; a personal loan EMI calculator like this one shows both side by side.
Car loan EMI calculator
When you use it as a car loan EMI calculator, enter the amount you will actually borrow after your down payment. In other words, a larger down payment lowers both the EMI and the interest you pay.
Education loan EMI calculator
Many education loans include a moratorium, which is a period during the course when no EMI is due. However, interest may still build up during that time, and the lender may add it to the loan. This education loan EMI calculator assumes repayment starts straight away. So, if your loan has a moratorium, ask your lender for the expected balance when repayment begins and enter that figure as the loan amount. Students can find more admission and scholarship coverage in our Education section.
What this EMI calculator does not include
The result is an estimate based on a fixed annual rate and monthly reducing-balance interest. A lender’s quote can differ because of:
- processing fees, documentation charges and GST on those fees;
- loan insurance premiums that the lender adds to the loan;
- part-prepayments or foreclosure;
- floating rates that change during the loan;
- moratorium or broken-period interest, and lender-specific rounding or day-count methods.
This page is for general information only and is not financial advice. Before you sign, ask the lender for the Key Facts Statement, which sets out the annual percentage rate and all charges. You can read more about consumer protection on the Reserve Bank of India website.
Frequently asked questions
How is EMI calculated?
EMI = P × r × (1 + r)n ÷ [(1 + r)n − 1]. Here P is the loan amount, r is the annual rate divided by 1,200 and n is the number of months. At 0% interest, the EMI is P ÷ n.
Why is my bank’s EMI slightly different?
Lenders may round each instalment, count days differently, add fees or insurance to the loan, or charge interest for a broken first period. Consequently, small differences of a few rupees are normal. Larger gaps usually point to extra charges, so ask the lender to explain them.
Is a lower EMI always better?
Not necessarily. A lower EMI often comes from a longer tenure, which increases the total interest. Instead, compare the total amount payable, not just the monthly figure.
Can I download the repayment schedule?
Yes. Select Download CSV to save every month’s EMI, principal, interest and closing balance as plain numbers. The file opens in Excel, Google Sheets or LibreOffice.
Does the EMI calculator save my information?
No. All calculations happen in your browser. We do not store or receive the numbers you enter, and neither does anyone else.
About this tool
JammuUniversity.in is an independent digital news publication. It has no affiliation with the University of Jammu, any bank or lender, or the Reserve Bank of India. This EMI calculator is a general-purpose estimation tool built for our readers, including students planning an education loan. Read more about us and our editorial policy, or browse our finance news. If you spot an error, please tell us through the contact page; we fix confirmed mistakes under our corrections policy.